
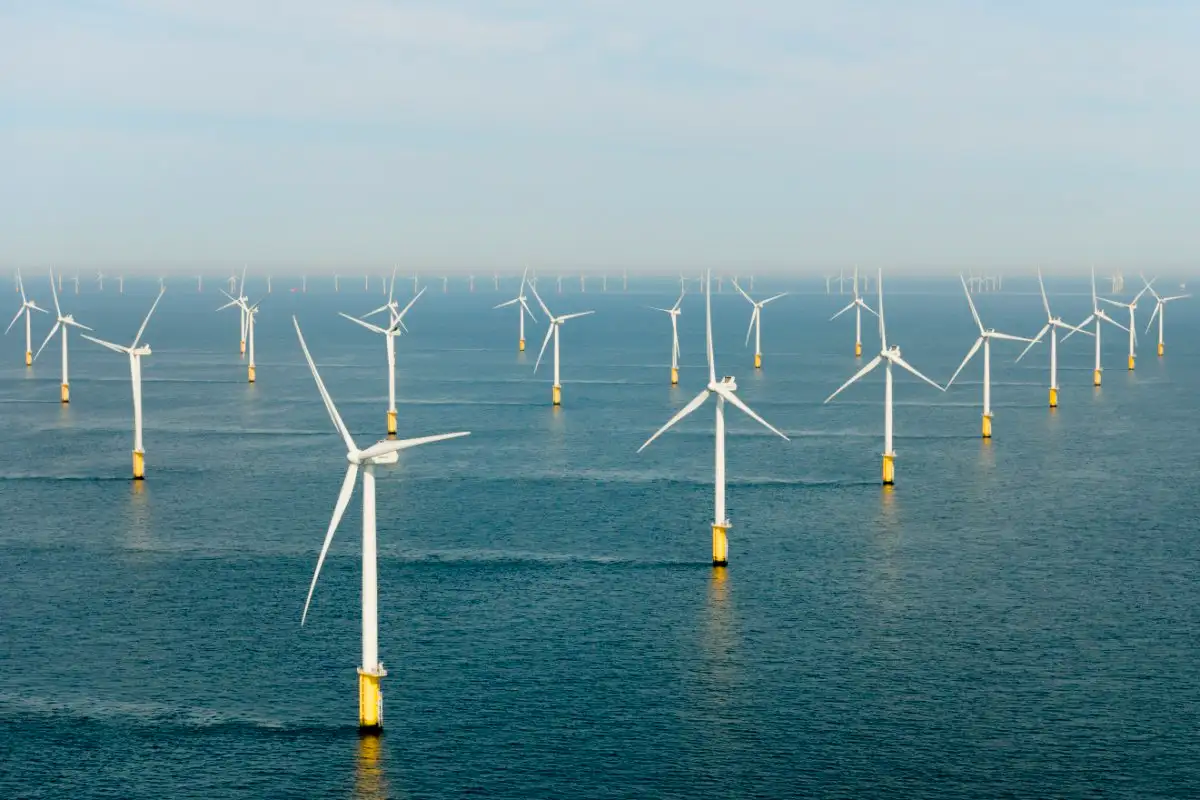
The Supreme Court of the United Kingdom has considered HMRC v Orsted, a significant tax dispute examining whether offshore windfarm development costs qualify for capital allowances under the Capital Allowances Act 2001.
The case focuses on the interpretation of section 11(4) and its application to major infrastructure projects in the renewable energy sector.
With a judgment dated 15 April 2026 and neutral citation [2026] UKSC 12, the appeal addresses the extent to which expenditure on surveys and studies can be treated as capital expenditure “on the provision of plant.”
The materials available provide insight into the legal issues and arguments considered by the Court.
The Dispute and Procedural History
The case concerns whether expenditure incurred on surveys and studies during the development of offshore windfarms qualifies for plant and machinery capital allowances.
The central issue is whether such costs constitute capital expenditure “on the provision of plant” under section 11(4) of the Capital Allowances Act 2001.
The respondent companies—Gunfleet Sands Limited, Gunfleet Sands II Limited, Walney (UK) Offshore Windfarms Limited, and Orsted West of Duddon Sands (UK) Limited—are engaged in the generation and sale of electricity from offshore windfarms.
Before construction commenced, they incurred significant expenditure on environmental, metocean, geophysical, and geotechnical studies. These investigations informed decisions relating to windfarm design, layout, installation, and construction.
The dispute progressed through multiple judicial stages. The First-tier Tribunal held that most of the disputed expenditure qualified for capital allowances.
The Upper Tribunal allowed HMRC’s appeal and concluded that the studies did not qualify. The Court of Appeal subsequently allowed the taxpayers’ appeal. HMRC then appealed to the Supreme Court of the United Kingdom.
The case ultimately turned on the correct interpretation of qualifying expenditure under UK tax legislation, specifically the meaning and scope of capital expenditure incurred “on the provision of plant” within the Capital Allowances Act 2001.
Legal Issues, Arguments, and Commercial Significance
At the heart of the appeal was the interpretation of section 11(4) of the Capital Allowances Act 2001, which provides that capital expenditure qualifies for allowances if it is incurred “on the provision of plant or machinery” for the purposes of a qualifying activity.
It was common ground between the parties that the expenditure in question was capital in nature and that the wind turbines and associated array cabling constituted “plant” for capital allowances purposes.
The central dispute therefore concerned whether the costs of surveys and studies undertaken during the development of offshore windfarms were sufficiently connected to the provision of that plant.
HMRC argued that the Court of Appeal had misinterpreted the statutory test, contending that qualifying expenditure must directly effect the provision of plant and should not extend to preparatory or investigative activities.
In its view, the phrase “on the provision of” requires a close and direct nexus between the expenditure and the actual provision of plant or machinery.
By contrast, the respondent companies maintained that the surveys and studies were integral to the design, installation, and construction of the windfarms, influencing the configuration and engineering of the generation assets and therefore forming part of their provision.
Both parties relied on established authorities interpreting capital allowances legislation, including IRC v Barclay, Curle & Co Ltd and Ben-Odeco Ltd v Powlson.
Beyond the legal dispute, the case carries broader commercial significance, highlighting the tax treatment of development costs associated with capital-intensive infrastructure projects.
Offshore wind developments require extensive technical and environmental studies, and the availability of capital allowances can materially affect project financing, investment decisions, and overall economic viability.
Consequently, the Supreme Court’s consideration of this issue is of particular relevance to corporate taxpayers, legal advisers, and investors operating in the infrastructure and renewable energy sectors.
Key Takeaways for Business
- Clarification of capital allowances law: The case examines the scope of qualifying expenditure under section 11(4) of the Capital Allowances Act 2001.
- Implications for renewable energy projects: It addresses the tax treatment of pre-construction costs in offshore wind developments.
- Impact on infrastructure investment: Companies undertaking capital-intensive projects must assess whether development studies qualify for tax relief.
- Compliance and documentation considerations: Businesses should evidence a clear nexus between preparatory expenditure and the provision of plant.
- Strategic guidance for advisers: The case provides insight into the boundaries of qualifying capital expenditure under UK tax law.
Judgment Status: The Supreme Court issued judgment on 15 April 2026 under neutral citation [2026] UKSC 12. However, the full reasoning and operative outcome are not included in the materials provided and are therefore not specified in this article.
Case Details
Court: Supreme Court of the United Kingdom
Date: 15 April 2026
Case Name: Orsted West of Duddon Sands (UK) Limited (now named Orsted Schroders Greencoat WODS Holdco Limited) and others v Commissioners for His Majesty’s Revenue and Customs
Docket Number: UKSC/2025/0069
Neutral Citation: [2026] UKSC 12
Area of Law: Tax Law / Capital Allowances
Legislation: Capital Allowances Act 2001, Section 11(4)
Status: Judgment issued; outcome not specified in the materials provided
People Also Ask
1. What is HMRC v Orsted about?
HMRC v Orsted concerns whether survey and study costs incurred during offshore windfarm development qualify for capital allowances. The case examines the interpretation of section 11(4) of the Capital Allowances Act 2001 and its application to renewable energy infrastructure.
2. What are capital allowances under UK tax law?
Capital allowances allow businesses to claim tax relief on qualifying capital expenditure, such as plant and machinery. These deductions reduce taxable profits and play a crucial role in corporate investment and financial planning.
3. Why is HMRC v Orsted significant for the renewable energy sector?
The case addresses the tax treatment of pre-construction development costs for offshore windfarms. Its outcome is important for energy developers and investors because capital allowances can materially affect project economics and investment decisions.
4. What does section 11(4) of the Capital Allowances Act 2001 provide?
Section 11(4) establishes the general rule that capital expenditure qualifies for tax relief if it is incurred on the provision of plant or machinery for a qualifying business activity.
5. Which courts heard HMRC v Orsted before it reached the Supreme Court?
The case progressed through the First-tier Tribunal, the Upper Tribunal, and the Court of Appeal before being heard by the Supreme Court of the United Kingdom.